New England Landmark Realty covers the Vermont real estate market 

from the inside — market data, buyer strategy, seller timing, land 

use regulation, and the policy decisions shaping what homes cost and 

who can afford them.


Tony Walton has been working Vermont real estate since 1978. 

The analysis here reflects that depth.


Browse by topic below, or use the search to find what you need.

Sept. 24, 2026

Stowe Short-Term Rental Rules: The 850-License Cap Is Now Law. What Buyers, Sellers, and Owners Need to Know

Quick Answer

Stowe did not ban short-term rentals. It capped them. The Selectboard adopted the Short-Term Rental Ordinance 5-0 in late July 2026. Beginning September 15, 2026, the Town issues no more than 850 general STR licenses, licenses do not transfer to a buyer, and new licenses come only through an annual July lottery. Owners whose primary residence is in Stowe can hold homestead licenses for up to two units outside the cap.

Key Takeaways

Two-Sentence Summary

Stowe's 850-license cap is now law, and the right to rent short-term stays with the owner, not the house. Buyers should value Stowe property without STR income they cannot yet license, and sellers should price for what a new owner can actually do.

If You Only Remember 3 Things

  1. An STR license does not transfer when the property sells, except to close family.
  2. New non-homestead licenses come only through the July lottery. The next one is in July 2027.
  3. Current license holders must renew by April 30 every year, starting April 30, 2027.

Quick Facts

  • Cap: 850 general STR licenses, starting September 15, 2026
  • Existing registrations: about 1,300, shrinking through attrition
  • Registration cutoff: 11:59 p.m., Monday, September 14, 2026
  • Lottery: forms June 1–30, drawing around July 15; 20 licenses in each of 2027 and 2028
  • Homestead limit: up to 2 units, outside the cap
  • Fee: $100 per unit for registration or renewal (as of August 2026)

Why a Cap Matters More Than a Registry

Registration adds cost. A cap changes value. Under the old registry, any buyer could register a home and rent it. Under the cap, the right to rent is scarce, and it does not come with the deed. Treat it like a water right that stays with the seller: the house may be identical, but the income stream is not.

If You Are Selling in Stowe

Your buyer cannot take over your license. Price and market the home on what a new owner can actually do with it: live there, rent it long-term, or enter the lottery. Buyers who modeled Airbnb income will adjust their numbers. Get ahead of that conversation with a clear, honest listing.

There is one exception. Licenses can pass between close family members, including spouses, parents, children, and grandchildren, without payment, into certain trusts, and at death to a relative who owns at least 10% of the property. If a family transfer is part of your plan, talk to your attorney before you move title.

If You Are Buying in Stowe

Do not underwrite a Stowe purchase on short-term rental income you do not yet have a license for. A non-homestead buyer gets a license only through the lottery, and the lottery offers very few licenses for now. Run your numbers on long-term rental or personal use. Count any future STR income as upside, not the base case.

If you will make Stowe your primary residence, the math changes. A homestead license lets you rent up to two units on your homestead property, outside the cap.

If You Already Hold a Stowe STR License

  • Renew on time. Licenses run May 1 to April 30. Your renewal is due by April 30, 2027, and every April 30 after that. Miss the deadline and you lose the ability to register that unit.
  • Watch how you hold title. The Town's guide says moving the property into an LLC or corporation voids the license. Get advice before you restructure ownership.
  • Keep the basics in place. Put your Town STR number in every ad. Keep a Fire Department-approved lockbox, such as a KnoxBox. Have a Designated Responsible Person who can respond in person within 45 minutes.
  • Fees: Registration and renewal are $100 per unit as of August 2026. The lottery fee has not been set yet.

Violations carry waiver fees of $100 to $400 and civil penalties of $200 to $800, rising with each offense in a 12-month period.

What Is Exempt

Designated resort areas are exempt from the ordinance. VTDigger reported that commercial properties in the ski and resort planned unit development zones, including Spruce Peak and the Trapp Family Lodge, fall outside it. Licensed lodging such as hotels, inns, and bed-and-breakfasts is also excluded, as are timeshares. For condos in or near those areas, confirm the exemption for the specific property with the Town before you rely on it.

How the Stowe STR Lottery Works

  1. Submit a lottery form and fee between June 1 and June 30.
  2. The Town draws by random number generator on or around July 15, livestreamed.
  3. If selected, submit your STR registration within 14 days of notice.

The next chance at a new license is the July 2027 lottery.

Frequently Asked Questions

Did Stowe ban short-term rentals?

No. Stowe capped general STR licenses at 850 starting September 15, 2026. Existing registrations moved over to licenses, and the total comes down through attrition.

Does a Stowe STR license transfer when I sell my house?

No. Licenses are not transferable in an arms-length sale. Limited transfers are allowed to close family members, into certain trusts, and at death.

How do I get a new STR license in Stowe?

Through the annual lottery. Forms are accepted June 1–30, and the drawing is around July 15. The Town's guide says 20 licenses will be issued in each of 2027 and 2028.

How many STR licenses can a Stowe resident hold?

Owners whose primary residence is in Stowe can hold homestead licenses for up to two units on their homestead property. These do not count against the 850 cap.

When do Stowe STR licenses renew?

Every year by April 30, starting April 30, 2027. The fee is $100 per unit as of August 2026.

What to Do Next

If STR income is part of your plan in Stowe, confirm the property's license status first. Then run the numbers without it. A plan that works without the license will hold up. A plan that needs a license you cannot get will not.

Questions on a specific Stowe property? Call New England Landmark Realty at 802-253-4711, or reach me directly at 802-233-4107. For the Town's side, contact STR@stowevt.gov or the Town Manager's office at 802-253-7350.

More from NELR: Vermont Home Buying Guide · Vermont Home Selling Guide · Vermont Real Estate Market Report · Vermont Closing Costs Guide

Sources

This post covers the ordinance as adopted in July 2026. It is not legal advice. Talk to an attorney about family transfers or changes to how you hold title.

Sept. 24, 2026

Williamstown Vermont Home Value, 2026: The Counter-Trend Buy Window

— the only Washington County market heading the other way, and what that means.

For buyers and sellers watching Vermont's affordable rung: Zillow's August 2026 ZHVI for Williamstown sits at $303,606, down 3.2% year-over-year, while the Realtor.com median list reads $411,000 — exactly where the rest of Washington County was twelve months earlier. This is a counter-trend market that rewards buyers who move before it re-enters alignment.

If You Only Remember 3 Things

  • Zillow's ZHVI sits at $303,606, down 3.2% year-over-year — the only Reading in central Vermont currently pulling back.
  • Movoto's mid-year 2026 median list cleared $411,000 against the $275,000 reading from 2025 — a list pricing move, but the sale trend hasn't matched the list.
  • The asset class below Washington County's main tier is buying window territory. A landlord or first-time buyer with a twelve-month horizon should be on the phone this season.

Every market in central Vermont except one is showing flat-to-up appreciation in 2026. Williamstown is the exception — down 3.2% year-over-year on Zillow's index, with Realtor.com and Movoto reporting a list median of $411K that hasn't yet converted to comparable sale prices. This is a buyer's market by every reading, and the only one in Washington County's broader tier. The window is open.

What is the median home price in Williamstown?

Two sources, a split story.

Zillow's August 2026 ZHVI for Williamstown sits at $303,606, down 3.2% year-over-year. That is the index's view of the underlying residential stock. Zillow's statewide zoom calls out Williamstown specifically at the same number. The index move year-over-year is the strongest pullback in central Vermont in 2026.

Movoto's July 2026 median list for Williamstown sits at $411,000 against $275,000 in 2025 — a list-price move that is materially ahead of sale-price movement. Realtor.com's Washington County market snapshot tracks similarly. The list premium reflects seller optimism in a market where buyers are not yet matching list. The list-to-sale ratio is the story here.

Is Williamstown finally a buyer's market?

Yes. The 3.2% YoY Zillow read and the gap between Movoto's $411K list median and 2025's $275K baseline both say the market is asking more than buyers are willing to pay. Inventory is expanding, DOM is loosening, and the price-reduction pattern is alive in the 30+ day listings.

That is the standard 2026 setup elsewhere; in Williamstown, it is the first year the asset class has tipped to clear negotiability.

How fast are homes selling in Williamstown?

Slower than Washington County's leading tier, faster than the rural Orange County boundary. Listings that priced at the Movoto-anchored median are absorbing that gap through either price reductions or DOM extension. Listings that priced closer to the Zillow ZHVI are clearing faster. The signal is: price to index, not to list-asking.

What makes Williamstown different from Northfield, Montpelier, or Barre?

Williamstown is Washington County's bottom-rung market, on the Orange County boundary, with more rural scale and less commuter accessibility. Northfield sits one tier up with Norwich University adjacency. Montpelier carries the State House walkable premium. Barre carries the granite industry legacy and the most affordable entry rung in Washington County proper. Williamstown sits at the bottom rung above Barre by a small margin on ZHVI but structurally closer to Orange County than to the Washington tier.

How does the rural-residential and multi-acre premium work?

Multi-acre rural properties in Williamstown trade on a different curve than the small-cap residential inventory. The rural tier tends to favor buyers who are willing to travel for land. The asset class doesn't move quickly in either direction, but it doesn't depreciate sharply either. The 3.2% YoY Zillow move is concentrated in the small-cap residential tier, not the multi-acre lot tier.

Should I bother with a valuation or just check Zillow?

Especially here. If you are a buyer, the Zillow read and the Movoto list read are telling different stories, and only a property-specific valuation gets to the answer. The Williamstown valuation tool is the second step. The third is the comp walk with Tony.

Questions buyers and sellers ask us about Williamstown

Will Williamstown prices keep falling?

National forecasts put 2026 price growth at three to four percent. Williamstown's 3.2% YoY decline will likely flatten through Q3 2026 and re-enter the broader band by Q4. The pullback is a one-year aberration, not a multi-year decline.

Is Williamstown affordable for first-time buyers?

At a $303,606 ZHVI and Movoto list reading we expect to settle into a $350K-$400K effective close band, with 5.9% to 6.2% mortgage rates, the monthly cost works on two-income households. Vermont State Housing Finance, USDA rural development loans, and Orange County first-time buyer programs all stack on the median. Talk to a local lender.

How does Williamstown compare to Northfield?

Northfield trades slightly above Williamstown at ZHVI, with Northfield's index at $324,071 versus Williamstown's $303,606. That gap is 6.4% — narrower than the gap in vibe. Northfield is mid-tier commuter; Williamstown is rural-residential on the Orange County boundary.

Should I sell now or wait until spring?

Spring is the strongest window for rural-residential pricing across Vermont. Williamstown is no exception. List late March through early May for the moving season's natural cadence.

Do you have clients who overpaid in 2022?

Yes. Several of them are refinancing now. Williamstown's pullback year hurts some owners acutely even as the long-run outlook flat-to-positive. The conversation for owners in that position is how to position the asset through the next three years until the market recovers the comparables.

Where to Go Next

New England Landmark Realty · 26 N Main Street Suite 2, Waterbury, VT 05676 · Office (802) 253-4711 · Toll-Free (866) 324-2427 · Tony's cell (802) 233-4107 · www.nelandmark.com

.

Sept. 23, 2026

Northfield Vermont Home Value, 2026: Washington's Hidden Buyer's Market

— Washington's most-read housing market is doing something the rest of the county isn't.

For buyers and sellers watching Washington's mid-tier towns: Zillow's August 2026 ZHVI for Northfield sits at $324,071, and Redfin's three-month rolling median sale cleared $314,000 through August, up 11.3% year-over-year. That's the strongest year-over-year move in Washington County this season. Here's how to use it.

If You Only Remember 3 Things

  • Zillow's August 2026 ZHVI for Northfield is $324,071, up 0.5% year-over-year, with 19 active listings on Realtor.com's August snapshot.
  • Redfin's three-month rolling median sale cleared $314,000 through August 2026, up 11.3% year-over-year — the strongest YoY reading in Washington County.
  • Realtor.com's median list sits at $325,000, with median DOM of 57 days — a real buyer's negotiating window is open.

Northfield has been the affordable rung on the Washington County ladder for a decade. The town gets fewer headlines than Waterbury, fewer campus buyers than Montpelier, and fewer ski-trail dollars than Morrisville. It has its own economy, anchored on Norwich University's housing demand, the Route 12 commuter axis, and a tight stock of small-cap residential. That mix is paying investors and first-time buyers around now.

What is the median home price in Northfield?

Two sources, two readings, both meaningful.

Zillow's August 2026 ZHVI for Northfield sits at $324,071, up 0.5% year-over-year. Realtor.com's August 2026 Washington County market report gives a median list of $325,000, with median DOM of 57 days, and a median rent of $1,600 per month.

Redfin's three-month rolling median sale is $314,000, up 11.3% year-over-year through August. That move is the strongest in Washington County, and it is what first-time buyers are responding to: affordable in absolute terms, strong YoY appreciation, and a meaningful list-to-close negotiation range given that DOM.

Is Northfield finally a buyer's market?

At a 57-day median DOM and 19 active listings competing against the local buyer pool, yes — Northfield has the most negotiating room of any Washington County town currently tracked. The 11.3% YoY median sale move is not contradicted by the DOM; it is exactly what you would expect to see in a market that has expanded the negotiation window while still moving because the underlying demand is real.

How fast are homes selling in Northfield?

Realtor.com's snapshot shows median DOM of 57 days against a median list of $325,000. That's slower than Waterbury (54 DOM but at a higher median) and slower than the walkable Montpelier tier. It is, however, well within range for a market where the median sale is up 11.3% year-over-year — the DOM drift reflects inventory expansion, not buyer hesitation.

What makes Northfield different from Montpelier, Waterbury, or Williamstown?

Northfield is Washington County's mid-tier commuter and Norwich-adjacent inventory pool. Montpelier is the State House walkable downtown. Waterbury is the I-89 commuter with ski-trail adjacency. Williamstown is the Orange County rural rung below the Washington tier. Northfield sits between Montpelier and Williamstown: more affordable than the State House market, more accessible than Orange County, with its own small-town identity.

The Northfield-Montpelier price ratio is roughly $324K ZHVI vs $423K ZHVI, with Northfield clearing 23% below the State House market for a smaller lot in a less downtown context. Same commuter pool, different asset class.

How does the Norwich University proximity premium work?

Properties within walking distance of Norwich's Sabre campus, or on the designated faculty-residential blocks, tend to demand a buyer pool of university-employed staff, contractors, and family-anchor renters. That pool is small but stable and runs year-round. Properties farther out toward Roxbury Gap or along Route 12 north trend toward the rural-Washington tier and price on a different curve.

Should I bother with a valuation or just check Zillow?

If you are a buyer, the Zillow index is a starting point. If you are a seller, or a buyer preparing to write an offer, the Northfield valuation tool is the second step. The third step is talking through the comps the AVM cannot see: the kitchen renovation, the lot line adjustment, the Norwich-adjacent factor that holds rents year-round.

Questions buyers and sellers ask us about Northfield

Will Northfield prices keep appreciating?

National forecasts put 2026 price growth at three to four percent. Northfield's current 11.3% YoY is the leading edge of an affordable rung running ahead of the broader market. We expect Northfield to settle into a four to seven percent YoY reading through 2026 as the early-YoY move normalizes.

Is Northfield affordable for first-time buyers?

At a $314K-$325K median band and 5.9% to 6.2% mortgage rates, the monthly cost works on two-income households. Vermont State Housing Finance programs and Washington County first-time buyer programs stack on the median. Talk to a local lender.

How does Northfield compare to Williamstown?

Williamstown trades slightly below Northfield at the ZHVI level, with the Zillow index at $303,606, down 3.2% year-over-year. The two towns are not direct substitutes; Northfield gives more commuter accessibility, Williamstown gives more rural scale.

Should I sell now or wait until spring?

The Northfield market rewards correct pricing at any season. We list to buyer intent: faculty turnover and young-family relocation cycle late winter to early spring. The downtown-home inventory clears at any season with the right price.

Do you have clients who overpaid in 2022?

Yes. Several of them are refinancing now. Northfield's 11.3% YoY means the leverage is better than it was in 2024, but the rate drag is still real.

Where to Go Next

New England Landmark Realty · 26 N Main Street Suite 2, Waterbury, VT 05676 · Office (802) 253-4711 · Toll-Free (866) 324-2427 · Tony's cell (802) 233-4107 · www.nelandmark.com

.

Sept. 21, 2026

Burlington Vermont Home Value, 2026: Chittenden's Tightest Year

— Chittenden County's water-side capital is still the most expensive housing market in Vermont.

For buyers and sellers watching Burlington and Chittenden County: Zillow's June 30, 2026 median sale for Burlington sits at $529,818, with the median list at $495,333. Redfin's three-month rolling read through August 2026 puts the median at $520K, up 0.9% year-over-year. The squeeze is real. Here's what's holding it up, and where buyers are still finding room.

If You Only Remember 3 Things

  • Zillow's Burlington median sale $529,818 (June 30 2026), median list $495,333 (July 31 2026); Redfin rolling three-month $520K (+0.9% YoY).
  • South Burlington tracks slightly below city at Zillow ZHVI $483,135, but Realtor.com's South Burlington list median is $748K — the South Burlington queue and infrastructure re-priced faster than the city itself.
  • Burlington is still Chittenden's tightest market and the only Vermont metro where bidding over ask remains a meaningful pattern in 2026.

Chittenden County carries roughly forty percent of Vermont's housing demand. Burlington carries most of Chittenden's. That is not an abstraction in 2026 — it is a pricing fact: when Washington County and Lamoille County are settling into flat-to-up-one-percent readings, Burlington is still pushing 1% to 2% year-over-year, and a small slice of the inventory is still trading above list. Not because the buyers are wild. Because the supply is not there.

What is the median home price in Burlington?

Three sources, three numbers, three real reads — each representing a different slice of the same market.

Zillow's June 30, 2026 median sale for Burlington sits at $529,818, with the median list at $495,333 as of July 31, 2026. The Zillow ZHVI is also a meaningful read in Chittenden because the actual transactions clear close to list more often than in any other Vermont metro.

Redfin's three-month rolling read through August 2026 puts the median sale at $520,000, up 0.9% year-over-year. Redfin's city-level read tends to weight more recent closings more heavily, which is why the figure runs slightly below Zillow's June 30 snapshot.

South Burlington, the suburb-adjacent inventory pool, sits at a Zillow ZHVI of $483,135, down 0.8% year-over-year. Realtor.com's snapshot of South Burlington lists a median of $748K — a meaningful gap that reflects the zip's newer construction and larger-lot inventory, not pricing weakness.

Is Burlington finally a buyer's market?

Not the way Washington County is. Chittenden is a market in slow re-equilibrium, not in retreat. Inventory has lifted across the metro, but the South End and Old North End walkups, the lakefront tier, and the UVM-adjacent family zone are still absorbing inside their comp range. Bidding over ask is still alive in that small tier. The over-ask share is small and concentrated at the upper end.

The South Burlington median list of $748K against the city list at $495K reflects the inventory split: the city is older housing stock with smaller footprints, the suburb is newer construction with larger footprints and infrastructure investment. The two answer different buyer demand.

How fast are homes selling in Burlington?

Faster than anywhere else in Vermont in 2026. South Burlington sits at Realtor.com median DOM around 22 days as the suburb has cooled slightly. The city itself runs within and around the 30-day window for walkup and family-zone inventory at the right price. The lakefront and Old North End tier clears inside a fortnight for comp-supported asking. The out-of-town buyer pool is alive, broadly financed, and ready.

What makes Burlington different from South Burlington, Winooski, or Essex?

Burlington is Vermont's largest city, lakefront-anchored, UVM-adjacent, walkable downtown city market. South Burlington is the suburb with newer construction and infrastructure. Winooski is the dense, urban-core, walkable but smaller-scale inventory pool immediately north. Essex is the family-suburb tier to the northeast.

The Burlington-South Burlington price read on Zillow runs about $529K vs $483K ZHVI for the city and the suburb respectively. The Realtor.com gap is wider because the South Burlington inventory includes newer construction that the city's missed. The buyer pool answers to different demand: the city wants the downtown, the suburb wants the new build, and Winooski is the urban-core alternative for the buyer who wants the scale without the city.

How does the lakefront and Old North End premium actually work?

If your property sits on Lake Champlain frontage or on a tier above Lake Street with view planes, the premium is real — typically 30% to 60% above the city median, depending on direct water access and lot depth. The Old North End walkable family zone clears at a smaller premium but holds its value through soft years better than the outer neighborhoods.

Should I bother with a valuation or just check Zillow?

If you are a buyer eyeballing a property, the Zillow index is a starting point. If you are a seller preparing to list, or a buyer preparing to write an offer, the Burlington valuation tool is the second step. The third step — the one that costs nothing and matters most — is talking through the comps the AVM cannot see: the kitchen and bath renovation bill, the Lake Champlain view plane that the next-door development might cut off, the UVM Medical Center adjacency that dwarfs the city's own comp set.

Questions buyers and sellers ask us about Burlington

Will Chittenden prices drop in 2026?

National forecasts put 2026 price growth at three to four percent. Chittenden is tracking inside that band but at the upper end. We expect Burlington to finish 2026 up one to two percent, lakefront tier up more, outlying tier up less or flat.

Is Burlington affordable for first-time buyers?

At the $520K median sale and 5.9 to 6.2 percent mortgage rates, the monthly cost is real, but the rental alternative is structurally weak, and Vermont State Housing Finance programs plus Chittenden-specific first-time buyer programs stack on the median. Talk to a local lender before self-selecting out.

How does Burlington compare to South Burlington?

South Burlington trades slightly below Burlington on the ZHVI but significantly above on Realtor.com's live list. That spread is the inventory mix. The suburb carries newer construction and larger lots; the city carries older walkups and lakefront heritage. The two are not directly comparable as asset classes.

Should I sell now or wait until spring?

List late winter through early spring to capture the UVM-area relocation window and the Boston / New York second-home capital that returns once the academic year settles. Burlington's absorption is year-round but peaks with the campus cycle.

Do you have clients who overpaid in 2022?

Yes. Several of them are refinancing now. If you are in that group, the conversation we are having is how to position the asset through the next three years until the market recovers the comparables.

Where to Go Next

New England Landmark Realty · 26 N Main Street Suite 2, Waterbury, VT 05676 · Office (802) 253-4711 · Toll-Free (866) 324-2427 · Tony's cell (802) 233-4107 · www.nelandmark.com

.

Sept. 18, 2026

Montpelier Vermont Home Value, 2026: What a Buyer's Market Looks Like

— an honest read on the smallest state capital in the country.

For buyers and sellers watching Central Vermont's capital: Montpelier sat at $423,230 on Zillow's August 2026 index, up 0.8% year-over-year, and the 05602 zip behind it cleared $435,695 on the same read. This is the first year since 2021 the city is showing real negotiating room. Here's why, and what to do about it.

If You Only Remember 3 Things

  • Zillow's August 2026 home-value index for Montpelier sits at $423,230, up 0.8% year-over-year; the 05602 zip underneath it is $435,695, up 0.7%.
  • Realtor.com's August 2026 snapshot puts median list at $423,000, with rents holding flat at $1,475 month (down 6.35% YoY in some zip readings).
  • Inventory has lifted enough that the market is finally showing negotiating room, but State House proximity and the walkable downtown still defend a premium that other Washington County markets don't.

The smallest state capital in the country has always priced on a different curve than its Washington County neighbors: less lot, more walkability, a tighter downtown housing stock, and a permanent renter pool feeding off the State House workforce. That has produced a market that moves sideways in soft years and the same buyers circling in hot years. 2026 is finally a sideways year worth paying attention to.

What is the median home price in Montpelier right now?

That depends on whether you trust Zillow's ZHVI land read or Realtor.com's live-list median.

Zillow's August 2026 home-value index for Montpelier sits at $423,230, up 0.8% year-over-year; the 05602 zip itself is currently $435,695, up 0.7% year-over-year per Zillow's most recent move. The East Montpelier zip adjacent to it is $469,339, up 1.4% year-over-year.

Realtor.com's August 2026 Washington County market report puts Montpelier median list at $423,000, with year-over-year movement close to 7.95% in some median-list-window reads. Median rent on Realtor.com sits at $1,475 per month, down year-over-year in some Washington County sub-zips.

The way we read it for clients: $423K is the index land, $423K is the live list median. The two numbers are converging, which means the listings that popped at the top of 2024 have absorbed down toward index reality more than the index has moved upward.

Is Montpelier finally a buyer's market?

Soften the announcement, but: sort of. Inventory has lifted enough that buyers have a credible comparison set, financing has settled at 5.9% to 6.2% nationally, and Vermont followed. The State House workforce has remained a steady renter pool but is no longer bidding the for-sale market into submission the way 2022 did.

The defensible Montpelier inventory — the small-cap inventory within walking distance of State Street — is still tight by count. The remote-cap and rural-edge properties are looser. Buyers weighing competitive offers against waiting need to know which category the address is in. The walkable downtown addresses are still seller-supported. The rural-edge tier in East Montpelier and the bedroom-zone are looser.

How fast are homes selling in Montpelier?

Slower than the ski-corridor markets, faster than the rural-edge markets. Realtor.com's Montpelier DOM figure has trended upward over 2026 alongside inventory expansion. The walkable downtown addresses, however, are absorbing inside 30 days at the right price. The rural-edge inventory over 30 days.

The honest rule is the one we use for every Vermont town: list at the price you can defend by comp, not the price you wish a buyer would tolerate. The Montpelier market is rewarding pricing discipline again.

What makes Montpelier different from Waterbury, East Montpelier, or Barre?

Montpelier is the state's capital with a walkable downtown and a State House workforce. That is the line we give every client who anchors Montpelier pricing against Waterbury or Barre expectations. They are different asset classes with different buyer pools.

Waterbury homes price on I-89 commute and ski-country proximity. Barre homes price on Vermont granite industry adjacency and Washington County's more affordable entry rung. Montpelier prices on State House workforce, State Street walkability, and the tightest downtown housing stock in the state. None of that translates between the three markets. The Waterbury-Montpelier price ratio runs about $543K ZHVI vs $423K ZHVI, with Montpelier commanding roughly 22% less for significantly more downtown access.

How does the State House proximity premium actually work?

If your property sits within walking distance of the State House, the downtown schools, or a State Street commercial block, stop comping against rural Washington County addresses. The premium is real — typically 25% to 40% above the rural and East Montpelier tier, depending on location and condition. Walkable Montpelier is the asset class. East Montpelier and rural Washington County are a different asset class and a different buyer pool.

Should I bother with a valuation or just check Zillow?

If you are a buyer eyeballing a property, the Zillow index is a starting point. If you are a seller preparing to list, or a buyer preparing to write an offer, the Montpelier valuation tool is the second step. The third step — the one that costs nothing and matters most — is talking through the comps the AVM cannot see: the kitchen that was gutted last spring, the slate roof that was replaced three years ago, the heating system that the seller just upgraded.

Questions buyers and sellers ask us about Montpelier

Will Vermont home prices drop in 2026?

National forecasts put 2026 price growth at three to four percent. Washington County is tracking inside that band but lower. We expect Montpelier to finish 2026 somewhere between flat and up one percent, with the walkable downtown addresses firm and the rural-edge tier softer.

Is Montpelier affordable for first-time buyers?

At the $423K to $435K index band and 5.9% to 6.2% mortgage rates, the monthly cost works for two-income households with stable employment. Vermont State Housing Finance programs, USDA rural development loans, and Washington County first-time buyer programs all stack on top of the median. Talk to a local lender before self-selecting out.

How does Montpelier compare to East Montpelier?

East Montpelier trades slightly above Montpelier's median Zhvi at $469,339, up 1.4% YoY. That gap is the rural-residential tier within commuting distance of the State House, with more land than downtown Montpelier, served by a different school district. The two markets are different asset classes and not always comparable.

Should I sell now or wait until spring?

List late winter through early spring for the State House workforce buying window. Inventory is rising but the State House office cycle does not pause for the season. The walkable downtown addresses clear year-round. We time listings to buyer intent, not to seasonal height.

Do you have clients who overpaid in 2022?

Yes. Several of them are refinancing now. If you are in that group, the conversation we are having is how to position the asset through the next three years until the market recovers the comparables.

Where to Go Next

New England Landmark Realty · 26 N Main Street Suite 2, Waterbury, VT 05676 · Office (802) 253-4711 · Toll-Free (866) 324-2427 · Tony's cell (802) 233-4107 · www.nelandmark.com

.

Posted in Market Updates
Sept. 17, 2026

We’re Choosing the Postcard


A Letter from Waterbury, Vermont

We’re Choosing the Postcard

On housing, property taxes, and second homes — and what kind of Vermont our kids inherit. Sent to my newsletter in January. Updated for September 2026. The numbers didn’t get better.

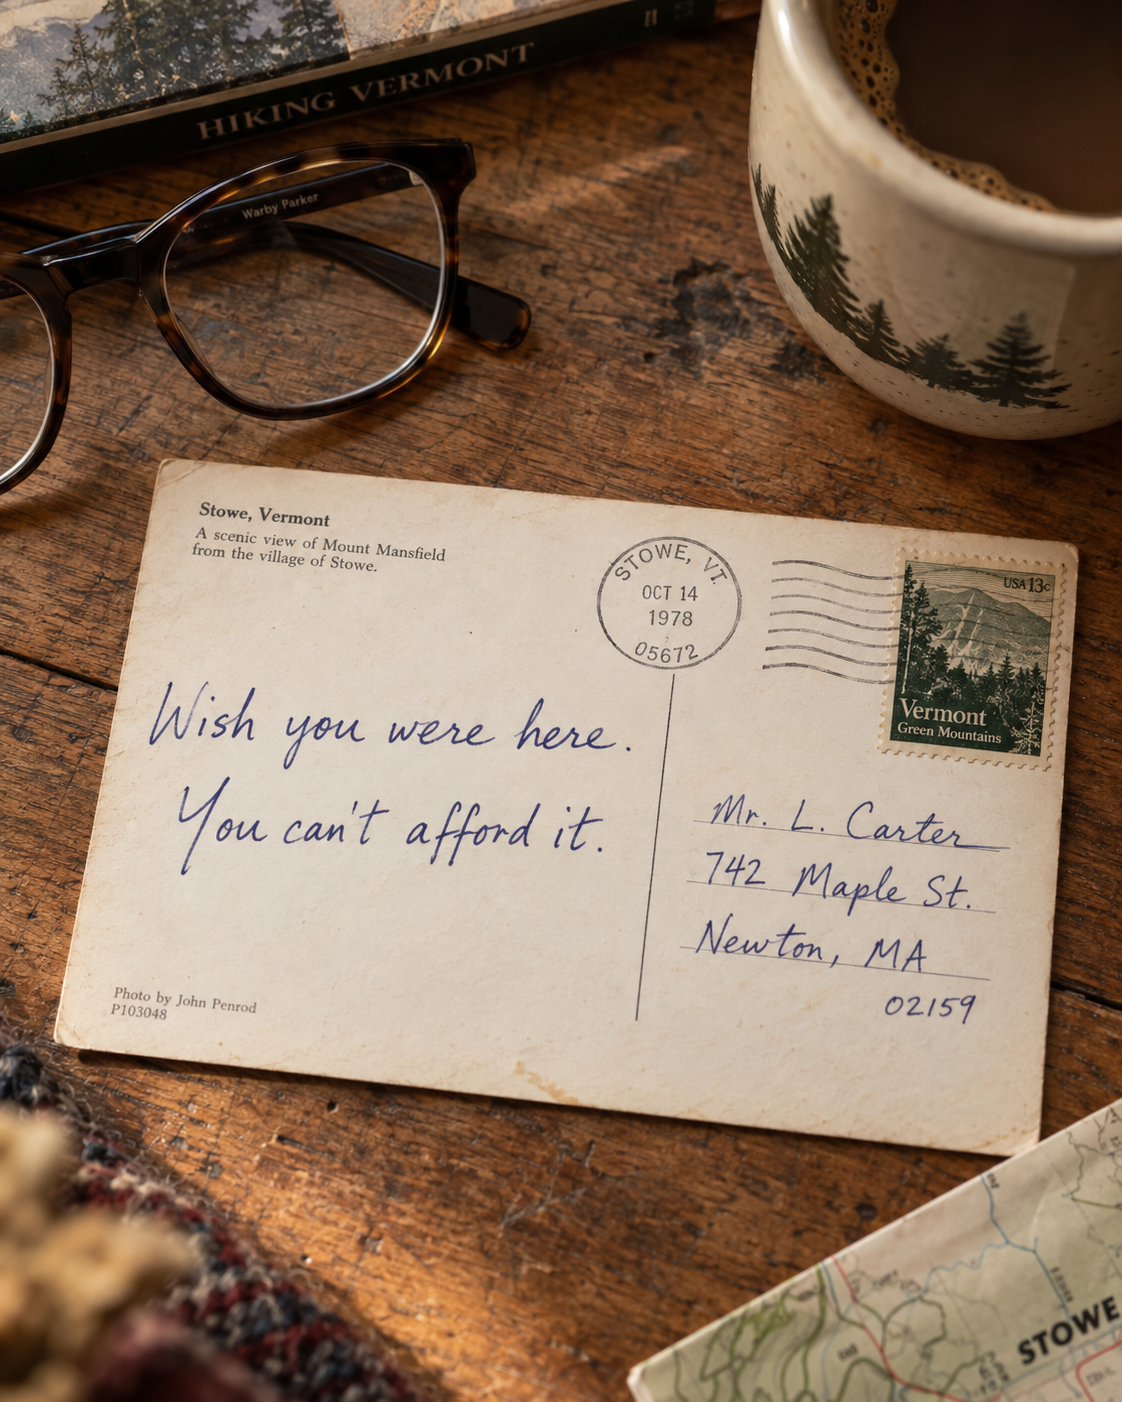
A vintage Vermont postcard on a wooden table beside reading glasses and coffee, handwritten in blue ink: “Wish you were here. You can’t afford it.” Postmarked Stowe, Vermont, 1978.
Found in a drawer in Waterbury. The front is a ski trail; the message side is the housing market.

I was 12 years old when my family moved to Vermont in 1978. I’ve lived in Arizona, Texas, North Carolina, and Idaho since then—but I’ve called Vermont home for nearly five decades. I came back full-time in 1998 with a belief that this was still a place you could build a life if you were willing to work hard and show up for your community. I’ve raised two sons here. I’ve served on nonprofit boards and sold real estate for over 20 years through the Great Recession, the COVID crash, and two housing bubbles. I love this place.

But I’m watching Vermont hollow out, and the conversation we’re having about why is mostly bullshit.

I wrote this in January and sent it to my newsletter. Some of you read it. Most of Vermont didn’t. Last week I checked every number again before posting it here, and here’s the thing: the numbers didn’t get better. Some got worse. A few changed shape entirely—and one of them will be on your ballot November 3rd.

Let me be clear: I’m a real estate broker. I’ve made a living selling homes to out-of-state buyers, second-home purchasers, and retirees with big-city equity. I’m not anti-wealth. I’m not anti-growth. I’m not some Bernie-bro socialist who thinks private property is theft.

But I’m also a Vermonter who chose to come back and stay, who watches essential workers leave because they can’t find housing, and who’s tired of pretending the market will magically fix a problem we’ve spent 20 years creating through policy choices that prioritize aesthetics over people.

So let’s stop lying to ourselves. Here’s what’s actually happening.

Part OneThe Museum Economy: When Vermont Becomes a Postcard, Not a Place

Vermont has become a museum for rich people to visit. We’ve built an economy that extracts value from elsewhere while making it impossible for the people who actually make Vermont function to afford to stay.

The math is brutal. Vermont’s median home price is now around $412,000—up roughly 148% since 2001 and still inching upward even as the market cools. Median household income over that same quarter-century? Up about 72%. It sits near $85,000 today. Which means over 90% of Vermonters cannot afford the median-priced home without being severely housing-cost-burdened.

The Brutal Math — Statewide, September 2026

Median home price≈ $412,000
Median household income≈ $85,000
Prices since 2001 / incomes since 2001+148% / +72%
Vermont renters who can afford to buy 6% (32% in 2021)
Rental vacancy rate 2.5%
Year-round homes still missing 24,000–36,000

Figures: Redfin (median price, early 2026); U.S. Census/FRED (median income); 2025 Vermont Housing Needs Assessment and VHFA (renter affordability, vacancy, shortfall) — compiled September 2026. Renter-affordability and vacancy figures reflect the latest published assessment data.

In 2019, a Vermonter earning the median income could afford roughly half the homes on the market. By 2024, that dropped to one-third. And if you’re a renter hoping to buy? Only about 6% of Vermont renters have the income needed to purchase a median-priced home, down from roughly a third in 2021. The rental vacancy rate is 2.5%. There is essentially nothing to rent and nothing to buy.

Translation: We’ve priced out the teachers, the nurses, the carpenters, the restaurant workers, the nonprofit staff—everyone who makes Vermont more than a scenic backdrop for weekend Instagram posts.

And here’s the twist nobody predicted: the market finally cooled, and it still didn’t fix anything. Inventory is up nearly 12% from last year. Homes are sitting a median of about 90 days. Sellers are getting around 96 cents on the dollar instead of bidding wars. For the first time since before the pandemic, this feels like a functioning market.

But prices are still climbing—because 2.9 months of supply is nowhere near the 4 to 6 months a balanced market needs, and the shortage underneath the cooling is still 24,000 to 36,000 homes. The ice melted. The water’s still freezing.

Part TwoThe Property Tax Trap (Updated)

Meanwhile, property taxes have risen roughly 40% over the past five years. This session the Legislature passed a $100 million one-time buy-down that cut the average projected increase from about 7% to about 3.5%. Homeowners breathed a sigh of relief.

They shouldn’t—not because the relief wasn’t real, but because of how it was bought. That’s the third straight year we’ve papered over structural costs with one-time money. That’s not a funding strategy. That’s burning the furniture to heat the house.

Homeowners are furious. They’re blaming school budgets. They’re showing up at town meetings demanding cuts. And I get it—when your tax bill jumps $1,200 in a year, you want someone to blame.

But here’s what nobody wants to say out loud: Your property taxes aren’t high because schools are greedy. They’re high because we stopped growing the tax base.

Student enrollment is down. We’re educating fewer kids than we were 10 years ago. But we’re trying to maintain 1970s-era school infrastructure across 200+ towns with half the population density to support it. And because we’ve blocked housing development, blocked commercial growth, and made it nearly impossible to build anything anywhere affordably, the taxable grand list hasn’t grown fast enough to spread those costs across more properties.

So we squeeze existing homeowners harder. And harder. Until they break.

That’s not a school spending problem. That’s a we-refuse-to-grow problem. The 2026 session’s education bill—seven new regional service areas, a new funding formula by 2030, and school construction aid restored for the first time since 2007—is real progress. But none of it works if the tax base keeps shrinking under it.

Part ThreeThe Second Home Conversation Nobody Wants to Have

Here’s the part where I lose some friends.

Vermont has a second-home problem. Not because second-home owners are bad people—many of them love Vermont as much as I do, contribute to local nonprofits, and spend money in our communities. But because when your vacation home sits empty 35–40 weeks a year while the teacher coaching your kid’s soccer team is commuting 45 minutes from another county because she can’t afford rent in town, we have a resource allocation problem.

The numbers, for the record, because the campaign rhetoric is already loose with them: Census data counts roughly 50,000 seasonal homes in Vermont—about 14% of our housing stock. VHFA’s analysis suggests about 35,500 are fit for year-round living. The Tax Department, casting a wider net, has flagged around 70,000 properties that could fall under a second-home tax. And about 12,000 properties operate as short-term rentals. Pick your number—every one of them is too high for a state that can’t house its nurses.

When I wrote this in January, the Legislature was still debating whether to reclassify second homes at all. Here’s where it actually landed: the 2026 education reform law wrote the third classification into statute. Homestead. Non-homestead nonresidential. And non-homestead residential—second homes. The framework is law. The rate isn’t set until 2029, it takes effect in 2030, and it disappears entirely if a future Legislature loses its nerve.

Meanwhile, the tools we already passed are underdelivering. The one-time tax on second-home sales has applied to roughly 7,300 purchases in two years and raised about $28 million—real money, but less than projected. The 3% short-term rental surcharge is collecting its pennies. We’re making progress at the speed of a zoning board of appeal.

And now the question goes to the ballot. Every Democrat who ran for governor or lieutenant governor this year campaigned on taxing second homes. The incumbents say they want to grow the tax base instead of adding taxes. The general election is November 3rd.

So here’s my ask of every candidate who knocks on my door this fall: Skip the slogan. Tell me the rate. Tell me the year. And tell me what you’ll do in 2029 when the postcard lobby calls it class warfare.

Because I’ll say what I said in January: when a wealthy out-of-state buyer outbids a young Vermont family by $50,000 because they can pay cash and plan to use the house six weeks a year, that’s not “the market working.” That’s wealth inequality playing out in real time, and pretending otherwise is cowardice.

I’ve sold second homes. I’ll probably sell more. But let’s not pretend there’s no tension here. If you’re going to own property in a place with a housing crisis, you’re going to help pay for the schools and services that make this a place worth owning property in. If that makes Vermont less attractive as a second-home investment? Good. We need homes for Vermonters more than we need more investment properties.

Part FourThe Building Problem We Won’t Name

Vermont’s own Housing Needs Assessment says we need somewhere between 24,000 and 36,000 additional year-round homes by 2029—the 40,000-by-2030 goal gets quoted too. In the past five years, we built fewer than 16,000 units. We are not going to make it. Not close.

Why? Because we’ve spent 50 years making it nearly impossible to build anything.

Act 250 was passed in 1970 to protect Vermont from becoming New Jersey. Noble goal. But it’s now a permitting gauntlet that adds 12–24 months and $40,000–$80,000+ to every project that triggers jurisdiction. The recent reforms (the new tiering system) are a step forward—they exempt some housing in designated growth areas. But they also increase scrutiny in rural areas, which is where most buildable land still exists.

And even without Act 250, you’ve got local zoning boards, design review committees, NIMBYs showing up to every public hearing to complain about “character” and “density” and “traffic,” and a culture that treats every new housing development like an existential threat to Vermont’s soul.

Here’s the thing: Vermont’s soul isn’t its zoning code. It’s the people who live here. And right now, we’re choosing aesthetics over people. We’re choosing “viewsheds” over teachers having a place to live. We’re choosing “I don’t want apartments near my house” over young families staying in the state.

The Legislature has also debated banning corporate entities from buying single-family homes in Vermont. It sounds tough. It feels good. And it will accomplish almost nothing, because Vermont’s housing problem isn’t Blackstone buying up subdivisions—it’s individuals outbidding locals, landowners sitting on buildable parcels waiting for appreciation, and towns blocking every development that comes before them.

Banning corporate buyers is political theater. It lets us feel like we’re doing something without confronting the hard truth: We are the problem. Our refusal to build. Our refusal to say yes to housing. Our refusal to accept that Vermont in 2026 can’t look exactly like Vermont in 1978.

Part FiveThe Coming Reckoning

Here’s what happens if we don’t fix this.

In 10 years, Vermont will be a state of retirees, remote workers with out-of-state incomes, and vacation homes. The median age will push past 50. The schools will consolidate further because there won’t be enough kids to justify keeping them open. The volunteer fire departments will collapse because there won’t be enough working-age adults to staff them. The restaurants and ski resorts will close early or reduce hours because they can’t find workers—because workers can’t find housing.

And the Vermonters who do stay will be the ones who inherited property or who are willing to be housing-cost-burdened at 50%+ of their income just to avoid leaving.

That’s not a functioning society. That’s a theme park with a property tax problem.

Some of you reading this will say: “Tony, you’re exaggerating. The market will correct. Supply and demand always balance out.”

No. They don’t. Not when policy strangles supply for decades. Not when wealth concentration allows a small number of buyers to outbid everyone else indefinitely. Not when “the market” is designed to allocate housing to the highest bidder, regardless of whether that person actually lives here.

The market is working exactly as designed. It’s just not designed to prioritize Vermonters.

Here’s the part the market optimists missed this year, though: Vermont just showed you what a real correction looks like, and it wasn’t a crash. Inventory rose. Days on market doubled. Sellers settled for 96 cents on the dollar. And median prices still went UP. That’s what a correction looks like in a state with a 25,000-home deficit. Even the relief rallies toward unaffordable.

Part SixWhat It Takes to Fix This (And Whether We Have the Guts)

I’m not naive. I don’t have a magic policy that solves this overnight. But I know what doesn’t work: pretending this is a temporary blip, blaming schools for tax increases, and blocking every housing development because it might change the view.

Here’s what actually moves the needle:

  1. Say yes to housing. Not just “affordable housing” in someone else’s town. All housing. Market-rate, workforce, senior, rental, ownership—everywhere, all the time. Because vacancy rates matter, and if you’re not building housing, you’re rationing it by price. And right now, locals are losing that auction.
  2. Finish the second-home tax. The framework is already law—the classification was written into statute this year. Now set the rate, set it before 2029, and make it survive contact with an election. If your property sits empty 40 weeks a year or operates as an Airbnb instead of housing Vermonters, you should pay more to support the community infrastructure you’re using. That’s not class warfare. That’s recognizing that housing has a social function beyond ROI.
  3. Reform permitting. Act 250 reform is a start, but it’s not enough. Local zoning needs to allow as-of-right development in growth areas—no design review, no conditional use hearings, no six-month appeals process. If it meets code, it gets built. Otherwise, we’re just pretending to care about housing while ensuring nothing actually happens.
  4. Use public land to build housing. The state’s inventory of state-owned land for housing should move faster. If private landowners won’t develop, the public sector should. And if that makes you uncomfortable, ask yourself: Why should your speculation matter more than a nurse’s ability to live near the hospital?
  5. Stop blaming schools and start growing the tax base. Education spending isn’t the problem—it’s that we’ve refused to build the housing and commercial tax base that funds education. You want lower property taxes? Build 5,000 housing units in the next three years. Watch what happens to your rate.

But here’s the real question: Do we actually want to fix this, or do we just want to complain about it?

Because fixing it means accepting that Vermont will look different. It means saying yes to housing developments that don’t look like restored 1850s farmhouses. It means higher density in town centers. It means your property value might not appreciate at 6% annually forever. It means second-home owners might pay more in taxes. It means some of the postcard aesthetics you moved here for might change.

And I’m not sure we’re willing to make that trade.

Part SevenThe Sliver of Hope (Because I’m Still Here)

Here’s what gives me hope: Vermonters have always been pragmatic problem-solvers when we stop posturing and start working.

I’ve watched this state rebuild after floods. I’ve watched small towns come together when someone loses a barn or a house. I’ve watched neighbors show up for each other in ways that would shock people from places where “community” is a marketing slogan.

That capacity is still here. The question is whether we’ll deploy it before it’s too late.

The new “Let’s Build Homes” nonprofit is a signal. Burlington’s housing push is a signal. The state inventorying public land is a signal. This year’s education law—with its restored school construction aid and its regional structure—is a signal. These are people refusing to accept that Vermont’s best days are behind it.

But signals don’t build houses. Political will does. Money does. Saying yes does.

And if we can’t muster that—if we keep choosing aesthetics over people, tax relief over growth, and nostalgia over survival—then we’re not solving a housing crisis. We’re managing a decline.

I didn’t come back to Vermont in 1998 to watch it become a museum. I came back because it was still a place you could build a life, raise a family, and be part of something bigger than yourself.

That’s still possible. But the window is closing.

So here’s my question for all of us—the longtime Vermonters, the new arrivals, the second-home owners, the developers, the selectboard members, the legislators, and everyone in between:

What kind of Vermont do you want your kids to inherit? A living, breathing community where working people can afford to stay? Or a scenic postcard where only the wealthy can play?

Because right now, we’re choosing the postcard. And we’re running out of time to change our minds.

Tony Walton

Principal Broker, New England Landmark Realty · Waterbury, Vermont

(802) 233-4107
Tony@nelandmark.com
nelandmark.com

If you want to talk about what’s actually happening in Vermont real estate—not the polished version, the real version—call me. If you want to yell at me for writing this, call me anyway. But if you want to pretend everything’s fine, save us both the time.

Sources: Redfin; Vermont Housing Finance Agency; 2025 Vermont Housing Needs Assessment; Vermont Department of Taxes; Vermont Public (Aug. 3, 2026); 2025–2026 Vermont legislative session summaries. Market figures current as of September 2026.
Sept. 17, 2026

Stowe Vermont Home Values in 2026: What 133 Closed Sales Actually Show

— a read of the actual 2026 Stowe MLS data. Every number in this post comes from the same file.

For buyers and sellers watching Vermont's ski corridor: 133 Stowe homes closed in 2026 at a $777,500 median, with single-family at $1.3M and condos at $597,500. 76% closed below list, 24% closed at or over list, and the active-to-pending inventory split is 138 to 14. The Mountain Road resort cluster (the ski-trail base) cleared $510,500 median in 107 days; village proper single-family cleared $1.3M median in 39 days.

If You Only Remember 3 Things

  • 76% of the 133 Stowe closings in 2026 closed below list price. The 101 "under list" sales averaged an $85,983 concession. The 32 "at or over list" sales averaged a $69,611 premium.
  • The market divide is geographic, not just about asset class. Mountain Road resort cluster median $510,500 / 107 DOM / $549 per sqft. Village proper single-family median $1,300,000 / 39 DOM / $449 per sqft. Two Stowe markets, one file.
  • Active-to-pending inventory is 138:14 — about 10% of active listings are under contract. Median list price across active listings ($997,000) is 28% above median close ($777,500). The ski-trailer market is saying no to listings that start too high.

The interesting thing about pulling the actual MLS file is not the median; it is what the median hides. Below is what 299 entries, 133 closed sales, 134 priced active listings, and 14 pendings actually tell us about Stowe right now.

What did 133 closed sales actually leave behind?

Of 299 rows in the active 2026 Stowe MLS sheet, 133 have a recorded close price and date. Together they are the most reliable read on what this town traded for — no aggregator weighting, no third-party index, just the data on the ground.

The headline: median close $777,500, mean close $1,159,470. That gap — $382,000 between mean and median — is the most important number in the file. The closing distribution is right-skewed: a handful of large Mountain Road and West Hill sales pull the average up while the typical Stowe property closed closer to the median.

By property type:

  • Single Family (n=53): median $1,300,000, mean $1,666,839, range $265,000 to $7,100,000. Top sale: $7,100,000 at 230 Belle View (18,055 sqft, single family). Second-highest: $4,450,000 at 685 Putnam Forest Road (6,456 sqft). Both sales ran on ski-corridor or ridge-view properties.
  • Condo (n=68): median $597,500, mean $813,691, range $20,000 to $4,425,000. The top condo sale of the year, $4,425,000 at 38 Inspiration Lane (3,000 sqft, DOM 11) cleared at a 5.4% premium over a $4,199,000 list — the ski-trail buyer paying through for the right asset.
  • Land (n=8): median $647,500, mean $803,875, range $439,000 to $1,500,000.
  • Multi-Family (n=1): median $950,000.
  • Commercial Sale (n=3): median $1,200,000, including 454 Mountain Road at $1.2M close on a $1.35M list, DOM 84.

The fractional sales you see — what they actually are

The three lowest condo closings in the file are $20,000, $58,000, and $78,000 at 580 Villa Drive (Stowe), all on a 2,543 sqft building representing fractional/quarter-share ownership. Close dates: 4/28/2026 ($20K), 2/3/2026 ($58K), and 3/25/2026 ($78K). These are not whole-condo comps. The $20K sale shows DOM 717 — the fractional market moves slowly.

The next tier of low condo closings sits at 7412 Mountain Road at $90,000 and $100,000 — same story. 7412 Mountain Road is a 312-unit resort-fee-managed building, and the low-dollar sales on that address are partial-ownership / timeshare transactions, not full-deed condos.

Backing the fractional-share sales out of the condo cohort changes the picture meaningfully. The whole-condo median clears closer to $725,000 on Stowe Mountain Road or slope-side stock, and reflects the actual full-ownership transaction price. Anyone comp-ing against the $20K and $58K lines on 580 Villa Drive is reading 580 Villa Drive as if it were living-residence inventory instead of a managed-fractional product.

The Mountain Road resort cluster is a separate market

The Mountain Road addresses cluster (1126, 454, 6047, 6049, 7412 Mountain Road) had 28 closed sales in 2026: median close $510,500, median 1,196 sqft, median $/sqft $549, median DOM 107 days. These are managed-resort, fractional-featured, ski-trail-adjacent assets. They price by rental yield and resort utility, not by primary-residence comp.

The slope-side ski-in/ski-out comp at Notchbrook tells a more conservative story:

  • 1277 Notchbrook Road — 1,700 sqft condo, closed at $690,000 against a $750,000 list, DOM 5.
  • 1307 Notchbrook Road — 1,700 sqft condo, closed at $710,000 against a $775,000 list, DOM 345.

Both Notchbrook trades cleared at roughly $400/sqft — significantly below the Mountain Road $549/sqft — because those are full-ownership ski condo comps without the resort-management-fee structure. Notchbrook is the right midpoint between Mountain Road's fractional-resort cluster and the village proper's primary-residence pricing.

Are buyers still overbidding?

The file answers this directly. Across all 133 closed sales:

  • 76% (101 sales) closed below list.
  • 24% (32 sales) closed at or over list.
  • Mean sale-to-list ratio: 92.7%.
  • Median sale-to-list ratio: 96.1%.
  • Average discount on under-list sales: $85,983.
  • Average premium on at-or-over-list sales: $69,611.

The overbid activity is concentrated in ski-trail positioning. The 38 Inspiration Lane trade at $4,425,000 against $4,199,000 list is one of the clearest ski-corridor premium still working in 2026.

The 76% under-list figure answers the most common 2026 buyer question directly: the ski-country second-home buyer is no longer paying over ask at the village scale. The sellers who started at the right number absorbed quickly; the ones who started high are taking the gap as time plus concession.

What's sitting right now, and what's under contract?

The sheet's live snapshot at the time of writing:

  • 138 active listings.
  • 14 pending.
  • 14 auction (auctions listed for visibility but not in standard absorption math).
  • 134 active listings have posted list prices; across them, median list $997,000, mean list $1,807,658. The mean is being pulled up by a single $11,500,000 listing on Mountain Road — without it, the active mean sits much closer to the median.

Theotype breakdown of active priced inventory:

  • Single family active (n=54 priced): median list $1,707,500, mean $2,765,898.
  • Condo active (n=54 priced): median list $522,000, mean $946,790.

The relevant comparison for any seller or buyer:

  • Active median list: $997,000.
  • Closed median: $777,500.
  • Active inventory is asking 28% above what closed.

The active-to-pending ratio of 138:14 means about 10% of the active cohort is currently under contract. That is a slow-absorption reading — typical ski-corridor markets in a hot year run closer to 25–35% under contract in this same ratio.

How fast are homes actually moving?

Across all 133 closed sales: median DOM 56 days, mean DOM 98 days. The distribution:

  • Under 30 DOM: 47 sales (35% of closings).
  • 30–60 DOM: 23 sales.
  • 60–180 DOM: 37 sales.
  • 180+ DOM: 26 sales.

By segment:

  • Single family: median DOM 39, mean 74.
  • Condo: median DOM 56, mean 115.
  • Mountain Road resort cluster: median DOM 107.
  • Village proper single family (non-Mountain Road): median DOM 39 days.

The fastest trades in the file: 685 Putnam Forest Road at $4,450,000 closed at list in DOM 0. 43 Nosedive Drive at $3,700,000 closed at list in DOM 0 (a 2,996 sqft condo). The 26 sales at 180+ DOM are listings that started above the eventual close and absorbed the gap over time.

What does this mean if you are buying or selling?

Buying. Pre-approval in hand before you write, because ski-corridor inventory priced correctly does not sit. The 35% of 2026 sales that closed in under 30 days went to prepared buyers with financing locked. If you are evaluating a Mountain Road fractional-share property against a village proper single-family, the comp set is wrong — those are not competing for the same buyer pool. Use Notchbrook or slope-side ski-only addresses as the actual ski-residence comp.

Selling. The 47 sales that closed in under 30 days started at the right price on day one. The 26 that took 180+ days absorbed the gap between original list and eventual close as time plus a discount through the listing window. The active median list of $997,000 against the closed median of $777,500 is a 28% gap that the market is currently demanding be closed either at the listing table or through the season's worth of push-back.

Practical starting point: list at 96–98% of what you actually need to bring home. The 76% under-list figure is the room the market is leaving you if you start higher; the question is whether you want that room as a price reduction or as a longer DOM.

What's the half-year pace?

Closings split by half-year, per the file:

  • H1 (Jan–June 2026): 120 closings.
  • H2 (Jul–Sep 2026, partial): 72 closings.

H2 is incomplete — only runs through mid-September. Expect the H2 closings count to scale to roughly 130–150 closings by year-end as the ski-season buying window opens in October and November. That puts the running full-year 2026 at approximately 250–270 closings against the H1 cadence of 120.

Questions buyers and sellers ask us about this data

What's the actual $/sqft by property type?

Single family at median $449/sqft (mean $464), n=53. Condo at median $435/sqft (mean $509), n=68. The Mountain Road resort cluster clears above both: median $549/sqft. The $/sqft gap between Mountain Road and the broader condo median is roughly $114/sqft — enough to add up to a $114K price difference on a 1,000 sqft asset. That gap is mostly the resort-fee infrastructure and ski-trail adjacency, and it is not captured by index-based single-median reads.

Should I trust Zillow, or just use the MLS?

Use the MLS for what you transact against. The Zillow ZHVI and Realtor.com market surveys are weighted-direction reads; they smooth out the ski-corridor premium and the resort-cluster $/sqft gap. The MLS file is the row-level truth.

If 76% closed under list, what should I list at?

List at 96–98% of what you actually need to bring home. The MLS data shows that the 101 under-list closings averaged an $85,983 concession. Listings that priced from the start under the eventual close absorbed quickly; listings that started higher absorbed the gap as time and discount through the season.

Does ski-season timing actually move price?

It moves absorption rate, not list price. A property that lists in October with ski-trail appeal draws Boston and New York second-home capital that is not in the market in May. At any given list price, the rate at which the property clears is what shifts seasonally.

What's my Stowe home worth right now?

If your property is single-family in the village proper: the typical 2026 close is $1.3M, 39 DOM, $449/sqft. If your property is on Mountain Road or in a slope-side cluster: $510K median at the bottom of the resort cluster, $549/sqft, 107 DOM. For a property-specific read, the Stowe valuation tool runs against the same data.

Where to Go Next

New England Landmark Realty · 26 N Main Street Suite 2, Waterbury, VT 05676 · Office (802) 253-4711 · Toll-Free (866) 324-2427 · Tony's cell (802) 233-4107 · www.nelandmark.com

.

Sept. 17, 2026

Waterbury Vermont Home Value, 2026: What the Numbers Actually Say

— fresh numbers and an honest read on where Waterbury sits this fall.

For buyers and sellers watching Central Vermont's I-89 corridor, the honest read on Waterbury today is this: the village held near $543K on Zillow's August 2026 index, Waterbury Center is pushing past $700K, and the days of bidding blindly over ask are finally over. Here is what the numbers actually say — and what to do before you list or write.

If You Only Remember 3 Things

  • Zillow's August 2026 home-value index for Waterbury sits at $543,015 — effectively flat year-over-year against Washington County's $403,250 county average.
  • Realtor.com's current listing median for the village is around $550K, holding in the mid-$500s while inventory measures itself out for the first time in three years.
  • Redfin's rolling three-month sale price for the broader Waterbury market closed around $357K by mid-summer 2026 — a number that reflects what sold, not what's listed, and the gap between ZHVI and sale price is the most important data point in this report.

The honest answer here is uncomfortable, and that is the point. Three data sources, three numbers, and three different stories about what is happening on Waterbury's Main Street corridor. The buyer or seller who anchors to the wrong one walks away with the wrong number in their head — and Washington County is the kind of market where that error costs you six figures.

What is the median home price in Waterbury?

That depends on which snapshot you trust. Three sources, three numbers, three different stories — and which one you anchor on will shape what you list at, offer at, or walk away from.

Zillow's August 2026 home-value index for Waterbury sits at $543,015 — effectively flat year-over-year at -0.6%. That is the headline number Washington County delivered while Chittenden was repricing upward and Lamoille was busy digesting the 2024 activity.

Realtor.com's current snapshot puts the village of Waterbury at a $550K median listing, with homes spending a median of 54 days on market at a $330 per-square-foot asking price. Recent sold data through Realtor.com shows 68 properties cleared at a $628,500 median, averaging 77 days on market. The spread tells you what Waterbury trades for once it's listed correctly.

Redfin's rolling three-month data for the broader Waterbury housing market closed June 2026 at $356,806 median sale price — down 11.6% year-over-year. The 05676 zip itself posted $465K median over the three months ending August 2026, down 18.5% year-over-year. Waterbury Center's 05677 zip, by contrast, posted $715K median over the same window, up 2.5% year-over-year.

The way we read it for clients: $543K is the Zillow ZHVI floor comp, $550K is the live listing median, $357K is the rolling sale price where the actual transactions land. Most village of Waterbury sales clear between the ZHVI and the listing median. Waterbury Center runs a different curve entirely. The Washington County backdrop sits around $400K, with 202 single-family sales closing in the first half of 2026 at a $400,000 median per Hickok & Boardman's mid-year market report.

Is Waterbury a buyer's market or a seller's market right now?

It is finally something we have not called in three years: a real market. Not a seller's market by force of inventory. Not a buyer's market by force of recession. A market where both sides do their actual jobs.

Inventory across Washington County eased enough to give buyers enough listings to compare. Mortgage rates settled between 5.9% and 6.2% nationally, and Vermont followed. The four-month supply reading the state is using this fall still tilts toward sellers — but only for well-priced homes in the village core.

The homes that sit are the ones that came on overpriced. The homes that move are the ones that came on right and let the comps do the negotiating. This is the first year in a decade Vermont is pricing like a normal residential market instead of a bidding war with closing dates attached.

How fast are homes selling in Waterbury?

The honest answer is two weeks for the right house and four months for the wrong one. The market is rewarding pricing discipline again.

The days-on-market data for the village of Waterbury has flattened out compared to 2024's frenzy. Realtor.com's recent sold data averaged 77 days end-to-end; the broader 05676 zip currently tracks around 54 days for fresh listings. We are back to a market where a buyer can inspect a property, sleep on it, and come back with a counteroffer. That has not been true since 2021.

The homes that trade under fourteen days are competing on price, condition, and lot. Buyers who lost out in 2022 and 2023 against cash-flush second-home buyers are now finding themselves back in the conversation — especially the ones who prepared their financing properly before they wrote.

What makes Waterbury different from Stowe, Montpelier, or Burlington?

Waterbury is Central Vermont's commuter town with ski access. That is the line we give every Boston relocation client who anchored pricing off Stowe or Burlington expectations. Those are different asset classes.

Stowe properties price on ski trails and second-home winter demand. Burlington prices on lakefront, downtown walkability, and UVM medical-center adjacency. Montpelier prices on State House adjacency and the capitol-region institution base. Waterbury prices on I-89 commute — Routes 89 and 100 converge here, Mansonville Park sits less than ten minutes north, and Stowe Mountain Resort runs thirty-five minutes up the valley. None of that delivers Stowe prestige, but it delivers Stowe access at Waterbury cost.

For buyers weighing Waterbury against Montpelier or Stowe, the comparison is different: commute, school system, lot size. Waterbury wins on lot and on I-89 access. Loses on walkable downtown density. Wins on price per square foot against Stowe. Loses on price per square foot against Montpelier. None of that is a deal-breaker. It is the tradeoff the buyer has to make explicitly.

How does the Waterbury Center and reservoir premium actually work?

If your property sits in Waterbury Center's 05677 zip, or has direct frontage on the Waterbury Reservoir, the Little River, or the Winooski's main stem — stop comping against village sales. The premium is real. Waterbury Center trades 80% above the village median; the reservoir and ski-corridor properties run 30% to 50% above village depending on lot depth, road access, and view plane.

The mistake buyers and sellers make most often is using a village cape sale as a comp for a Waterbury Center home, or a reservoir property sale as a comp for a cape. They are not the same asset. They are not the same buyer pool. They do not behave the same in a slow year.

Should I bother with a valuation or just check Zillow?

If you are a buyer eyeballing a property, the Zillow index is a starting point. If you are a seller preparing to list, or a buyer preparing to write an offer, the Waterbury valuation tool is the second step.

The third step — the one that costs nothing and matters most — is talking through the comps the AVM cannot see: the kitchen that was gutted last spring, the septic that needs replacement, the road that was re-paved since the last sale.

Zillow does not know about any of that. The MLS comps we pull every week do. The buyer who shows up to an offer with our valuation in hand and the seller's actual condition notes in mind is the buyer who wins the negotiation without paying the over-asking premium that ended 2024's deals.

Questions buyers and sellers ask us about Waterbury

Will Vermont home prices drop in 2026?

National forecasts for 2026 put price growth at three to four percent. Vermont's Washington County has held a narrower range. We expect the village of Waterbury to finish 2026 somewhere between flat and up two percent — gains driven by the low end of inventory tightening, not by the high end appreciating further.

Is Waterbury still affordable for first-time buyers?

Under a $400K median and 5.9% to 6.2% mortgage rates, the monthly cost is real but the structure works. Washington County first-time buyer programs, USDA rural development loans, and Vermont state housing finance programs all stack on top of the median. Talk to a local lender before you self-select out.

How does Waterbury compare to Waterbury Center?

The village of Waterbury is the walkable downtown — restaurants on Main Street, the railroad heritage, the Round Church, and a denser residential pattern. Waterbury Center is the surrounding rural-residential geography that rises north and east toward Stowe. They are two halves of the same town, and they trade at materially different price points. Waterbury Center currently leads the village by roughly 80% on median sale price.

Should I sell now or wait until spring?

Inventory is rising but the ski-season rental window is opening. We time listings to buyer intent: a primary residence lists early spring; a lake or reservoir property lists when the docks are visible; a ski-corridor property lists late summer. There is no universal answer — talk through your specific property and we will tell you when.

Do you have clients who overpaid in 2022?

Yes. Several of them are refinancing now. If you are in that group, the conversation we are having is not whether to sell. It is how to position the asset through the next three years until the market recovers the comparables. We do this every week.

Where to Go Next

New England Landmark Realty · 26 N Main Street Suite 2, Waterbury, VT 05676 · Office (802) 253-4711 · Toll-Free (866) 324-2427 · Tony's cell (802) 233-4107 · www.nelandmark.com

.

Sept. 16, 2026

Central Vermont Real Estate Market Update — September 2026

Central Vermont Real Estate Market Update — September 2026: The Fed Hikes as Mortgages Cross 7%

The Federal Reserve raised rates for the first time in three years on the very afternoon Washington County’s market turned positive year-over-year. Here’s what today’s hike means for buyers and sellers in Central Vermont — and why the two-speed market at 7% rewards the disciplined.

Tony Walton

Breaking: The Fed Just Hiked — September 16, 2026

At 2:00 PM ET today, the Federal Open Market Committee voted 12–0 to raise the federal funds rate by a quarter point to 3.75%–4.00% — the first rate hike in three years and the first of Chairman Kevin Warsh’s tenure. The FOMC statement cites inflation that “remains elevated,” and the central bank’s own projections (the dot plot) show the median official expecting one more hike this year.

Here’s the part that matters more than the headline: your mortgage rates had already crossed 7% before the Fed even voted. The bond market priced this hike in weeks ago. Daily rate indexes read roughly 7.00%–7.02% on a 30-year fixed this week, the 10-year Treasury touched 4.96% on September 11 before easing under 5% on the decision, and Warsh’s 2:30 press conference — his first as chair, with no forward guidance promised — is the variable that decides whether this is a one-and-done or the start of a new cycle.

The One-Line Read

Since August 19, Central Vermont turned the corner — prices flipped positive year-over-year and sales volume jumped. But the Fed just slammed the brake on the rate side, and 7% mortgages change the fall math for everyone in this market. The two-speed market — premium property strong, marginal property stalling — just sharpened. The window is no longer widening. It’s closing, on schedule and on cue.

The Numbers That Matter — Now vs. August 19

Mortgage rates: the binding line has been breached

The 30-year fixed-rate mortgage averaged 6.76% the week of September 10, 2026 (Freddie Mac weekly survey), up from 6.67% in mid-August — and daily index readings are above 7%. The federal funds rate now sits at 3.75%–4.00% after today’s hike. With the 10-year Treasury yielding near 5%, mortgage rates are at their highest in over a year, and the direction of travel is up until the data says otherwise.

Washington County: prices re-accelerated

Washington County’s median sale price rose to $409,878 over the three months ending August 2026, up 4.4% year over year — a decisive flip from the −0.9% reading in June. Sale-to-list holds at 98.0%, median days on market is stable at 53, and sales volume jumped to 91 homes in August vs. 80 a year ago. This is the strongest bellwether data in the state: a healthy market with manners, not a frenzy.

Vermont statewide: positive again, inventory still climbing

The statewide median rose to $438,280, up 0.8% year over year (Redfin, August 2026), flipping from the −2.0% reading of June. There were 3,869 homes for sale, up 14.2% year over year, with 862 new listings, up 11.4%. Months of supply sits at 5 months — dead on the balanced-market boundary. About 19.6% of Vermont homes sold above list price, down 2.9 points year over year: bidding is cooling, but values are not.

Waterbury: a caveated reading (small sample, don’t panic read it)

Waterbury’s all-property-types median came in at $375,000, down 34.5% year over year over the three months ending August — but treat this number as noise, not signal. Waterbury sees only 6–9 sales a month across condos, land, and single-family homes, so a single high-value closing swings the median by tens of thousands of dollars. The corroborating data tells a steadier story: price per square foot is $197 (−19.9% YoY), Zillow’s home-value estimate holds at $543,015 (−0.6%), and the brokerage single-family lane printed a $655,000 median in Q2 with sales up 100% year over year. The honest read: actual houses in Waterbury village still command real money; the long tail of condos, land, and overpriced rural listings is stalling — a microcosm of the two-speed market.

What This Means for Buyers — September 2026

If you’ve been waiting for a better moment, the calendar is no longer your friend. The Fed just put a deadline on indecision.

Lock a rate now — and buy it down

A $400,000 mortgage at 7.00% costs roughly $90 more a month than the same loan at August’s 6.67%. At 7%, one discount point — about $4,000 on a $400,000 loan — typically buys a quarter-point of rate relief and about $65 back on the monthly payment for the life of the loan. That is the single highest-value concession in this market, worth more than a $10,000 price cut.

A fully underwritten pre-approval is now the difference

At 7% and rising, sellers sort for certainty. The buyer with a clean, fully underwritten file and an executed rate lock wins against a higher offer with financing risk. Get the file clean before you shop, not after.

Shop the stalled listings, not the hot villages

The leverage lives in the 90–126-day listings and the overpriced inventory — exactly where the Waterbury all-types backlog sits. A clean offer at 96–97% of list on a sitting property, with a buydown ask, still works. Fast-moving, well-priced village homes are not negotiating much and just got harder, not easier.

The inspection trifecta — plus one — still non-negotiable

Flood and elevation certificates, septic and water tests, broadband speeds, and short-term rental permit status all need to be in writing before you write an offer. The Barre North End recovery remains stalled — federal funding denied again in April, and only 1 of 18 North End buyout applications approved — so flood-zone property is a different asset class than it was in 2022. Get the elevation certificate and the FEMA zone in hand.

What This Means for Sellers — September 2026

The market still works for the right property. The fall peak just narrowed.

List before Halloween, priced at or under September comps

Rates crossing 7% caps the rate-sensitive demand band and stretches days on market for marginal inventory. October is the last month with genuine foot traffic before the election lull and the December freeze. The buyers who can close at 7% are real but fewer — price to bring them in.

Condition is the price

With 3,869 homes statewide and buyers touring more before committing, deferred-maintenance listings are the ones stacking 90–126 days while move-in-ready homes in the same town sell in under 60. Invest in the list-day presentation — staging, professional photography, disclosure documents assembled — before you set the number.

Disclose everything, early

Flood history, elevation certificate, septic design, broadband. At 7% and rising, buyers have the patience and the options to walk away from surprises — and the leverage to renegotiate after inspection. A fully disclosed file is a competitive advantage in a market where trust is the scarcest commodity.

The Three Forces to Watch Through the Fall

1. The next move out of Washington

Today’s dot plot shows one more hike this year; Bank of America sees up to three (October and December). If Warsh frames today as one-and-done, expect the 10-year to pull back and rates to soften toward 6.6–6.8% into spring. If he signals a cycle, expect 7.25%+ and a wider two-speed market through winter.

2. A fall flood event

Northeast extreme-precipitation trends continue. Another Montpelier- or Barre-scale storm would re-price flood-zone assets overnight and compress values for a full year — while properties outside the 100-year floodplain suddenly command a premium.

3. Act 250 Tier 2 & 3 reforms — December 31, 2026

Statewide land-use review expands with the implementation of Act 181 (2024) and Act 152 (2026). Developable land may reprice upward ahead of the deadline while projects mid-permit face new friction. If you’re buying or selling land with development intent, the timing matters more than the comps.

The Bottom Line

This morning it was “the most generous negotiating window of the year.” This afternoon it’s “the last rate you may lock this year — maybe longer.” The fundamentals haven’t cracked — prices are up 4.4% in Washington County on 5 months of supply. But the Fed just put a deadline on indecision. Buyers who are qualified and know their towns should move before the next dot lands. Sellers should bring their A-game on price, condition, and disclosure now, because the margin for pricing mistakes just got thinner. In a two-speed market at 7%, discipline doesn’t just beat speed. It’s the only thing that beats it.

Vermont Real Estate FAQ — September 2026

Is now a good time to buy a house in Central Vermont?

For qualified buyers, yes — and the case is time-sensitive. Prices have turned positive (Washington County +4.4% year over year), inventory is at 5 months of supply, and the Fed just raised rates for the first time in three years with mortgages already above 7%. Every month of waiting risks another rate hike and another point of price growth. Shop the stalled listings, buy down the rate, and move on a clean underwriting file.

What did the Fed do in September 2026 and how does it affect mortgage rates?

On September 16, 2026, the Federal Reserve voted unanimously to raise the federal funds rate by 25 basis points to 3.75%–4.00% — the first hike since 2023. Mortgage rates had already priced in the move and now sit above 7% on 30-year fixed loans, tracking the 10-year Treasury at roughly 5%. The Fed’s projections show one more hike this year; some banks expect more.

What is the median home price in Washington County, VT right now?

Washington County’s median sale price was $409,878 over the three months ending August 2026, up 4.4% year over year. Sale-to-list holds at 98.0%, and homes spend a median of 53 days on market. Vermont’s statewide median was $438,280, up 0.8% year over year.

Will Vermont home prices drop in 2026?

A broad statewide drop is unlikely. Prices just re-accelerated (Washington County +4.4% YoY; Vermont +0.8% YoY), supply sits at 5 months — the boundary of balance, not above it — and rates now pose an affordability headwind rather than a crash trigger. Expect slow appreciation with possible flat spots, not declines.

Is Vermont a buyer’s market or seller’s market right now?

Vermont remains a seller-aligned market with buyer-friendly edges. Prices are rising, sale-to-list is 98%, and premium homes still move quickly. But above-list bidding has cooled to 19.6%, inventory is at a multi-year high, and days on market are stretching — especially on marginal, overpriced, or flood-affected properties.

Why did Waterbury’s median price drop so much in 2026?

Waterbury’s all-property-types median fell 34.5% year over year on a three-month window ending August 2026 — but the number is driven by a tiny sample (6–9 sales a month across condos, land, and single-family homes). Zillow’s home-value estimate for Waterbury is flat at $543,015, and broker single-family data shows a $655,000 median with sales up 100%. Read it as small-sample noise and a stalling marginal inventory, not a town-wide decline.

How long are homes sitting on the market in Vermont?

Median days on market are around 53 in Washington County and 64–91 statewide depending on the source and window. Some overpriced and marginal listings now sit 90–126 days. Well-priced, move-in-ready homes in demand towns still sell in under 60 — and under two weeks in places like Chittenden County.

How does Vermont flood history affect a home purchase in 2026?

Flood-zone status remains a material line item — especially along the Winooski and Stevens Branch rivers and in the Barre North End, where 2023 and 2024 flooding damaged more than 200 homes and recovery funding has stalled. Buyers should request an elevation certificate, ask about recent high-water marks, and check FEMA maps before writing an offer.

About the Author

Tony Walton is the Founding Partner and Principal Broker of New England Landmark Realty, serving Washington, Lamoille, and Chittenden Counties in Central Vermont since 2007. A former professional chef trained at the Texas Culinary Academy, Tony brings precision, creativity, and the calm of a dinner rush to every closing. Reach him at 802.233.4107 or through nelandmark.com.

Sources & Method

  • Federal Reserve FOMC statement — September 16, 2026 (federal funds rate raised 25 bps to 3.75%–4.00%, unanimous 12–0).
  • Yahoo Finance FOMC live coverage — September 16, 2026 (first hike since 2023; dot-plot median projects one more hike this year).
  • Freddie Mac Primary Mortgage Market Survey — week of September 10, 2026 (30-year fixed 6.76%; 15-year 6.09%).
  • Bankrate / Yahoo Finance (Curinos) daily mortgage rate indexes — September 15–16, 2026 (30-year fixed ~7.00–7.02%).
  • Redfin Washington County housing market — data through August 2026 (median $409,878, +4.4% YoY; 53-day DOM; 98.0% sale-to-list; 91 homes sold in August).
  • Redfin Vermont statewide housing market — data for August 2026 (median $438,280, +0.8% YoY; 3,869 homes for sale, +14.2%; 862 new listings, +11.4%; 5 months supply; 19.6% sold above list).
  • Redfin Waterbury housing market — data through August 2026 (median $375K all types, −34.5% YoY; 126-day DOM; 96.3% sale-to-list; $197/sq ft).
  • Zillow Waterbury Home Value Index — updated August 31, 2026 ($543,015, −0.6% 1-year).
  • CBS News — Fed rate hike and mortgage rates; 10-year Treasury 4.80% (Sept 8) rising to 4.96% (Sept 11).
  • Coldwell Banker Stowe/Waterbury Q2 2026 Market Report — single-family medians and DOM for Stowe, Waterbury, and Lamoille County North.
  • Catalyst Realty Collaborative — Chittenden County housing update (June 2026 median — $525K; 2.4 months supply; 6-day average DOM).
  • Vermont Act 250 Modernizing Land Use Review (Act 181 / Act 152) — jurisdictional tier phase-in dates.
  • VTDigger reporting (May 1, 2026) on Barre North End flood-recovery funding denials.

Article current as of September 16, 2026. Figures are pulled from the most recent monthly and quarterly reports available at publication, including same-day FOMC coverage. Buyers and sellers should request property-specific data before making decisions.


Sept. 16, 2026

Morristown Vermont Home Value, 2026: What the Numbers Actually Say

— fresh numbers and a real read on where Morristown sits this fall.

For buyers and sellers watching Vermont's Lamoille County, the honest read on Morristown today is this: the valley has stabilized above $371K, ski-country inventory is loosening for the first time in three years, and the deals trade before the listing aggregators pick them up. Here is what the numbers actually say — and what to do before you list or write.

If You Only Remember 3 Things

  • The Morrisville zip hit $371,300 on Zillow's July 2026 index, up 1.5% year-over-year — slower than Chittenden, faster than Washington County.
  • Lamoille County inventory rose enough to give buyers their first real negotiating window since 2022 — but well-priced homes still trade inside two weeks.
  • Lake Lamoille and reservoir properties price 30–50% above the median; if you are comping against a non-water address, that gap is the mistake you are about to make.

The honest answer here is uncomfortable, and that is the point. Three data sources, three numbers, and three different stories about what is happening on the Lamoille valley floor. The buyer or seller who anchors to the wrong one walks away with the wrong number in their head — and Vermont is the kind of market where that error costs you six figures.

What is the median home price in Morristown?

That depends on which snapshot you trust. Three sources, three numbers, three different stories — and which one you anchor on will shape what you list at, offer at, or walk away from.

Zillow's July 2026 home-value index for Morrisville sits at $371,300 — up 1.5% year-over-year. That is the gentle bump Vermont's central valley delivered while Chittenden was busy repricing itself upward and Washington County was busy digesting the 2024 numbers.

Realtor.com's August 2026 market survey put Morrisville at a $410K median, with active inventory down 3.65% year-over-year. That number counts what is listed this week, not what closed. It is a current-temperature reading, not a trail.

Redfin's county-level report for the three months ending August 2026 put Lamoille County at $642K — the high mark that reflects Stowe and Eden resort-property weighting. Read it wrong and you will overprice your Morrisville cape by $200K.

The way we read it for clients: $371K is the floor comp, $410K is the market median, $642K is the ceiling where ski-country luxury lives. Most in-town Morristown sales land between the first two; the upper Lamoille aggregate is a different asset class entirely.

Is Morristown a buyer's market or a seller's market right now?

It is finally something we have not called in three years: a real market. Not a seller's market by force of inventory. Not a buyer's market by force of recession. A market where both sides do their actual jobs.

Inventory across the Lamoille valley rose enough this year to give buyers enough listings to compare. Mortgage rates settled between 5.9% and 6.2% nationally, and Vermont followed. The four-month supply reading the state is using this fall still tilts toward sellers — but only for well-priced homes in Morrisville's walkable core.

The homes that sit are the ones that came on overpriced. The homes that move are the ones that came on right and let the comps do the negotiating. This is the first year in a decade Vermont is pricing like a normal residential market instead of a bidding war with closing dates attached.

How fast are homes selling in Morrisville?

The honest answer is two weeks for the right house and four months for the wrong one. The market is rewarding pricing discipline again.

The days-on-market data on Morrisville listings has flattened out compared to 2024's frenzy. We are back to a market where a buyer can inspect a property, sleep on it, and come back with a counteroffer. That has not been true since 2021.

The homes that trade under fourteen days are competing on price, condition, and lot. Buyers who lost out in 2022 and 2023 against cash-flush second-home buyers are now finding themselves back in the conversation.

What makes Morristown different from Stowe, Waterbury, or Morrisville proper?

Morrisville is the working town inside a resort geography. That is the line I tell every client who flies in from Boston assuming Stowe pricing covers the whole valley. It does not.

Stowe properties price on ski trails and second-home winter demand. Morrisville prices on year-round residents, Route 100 commuter traffic, and Copley Hospital proximity. They are not the same town, and they are not the same asset class.

For buyers weighing Morristown against Waterbury or Montpelier, the comparison is different: commute, school system, lot size. Morristown wins on lot. Loses on walkable downtown. Wins on price per square foot. Loses on perceived prestige. None of that is a deal-breaker. It is a tradeoff the buyer has to make explicitly.

How does the Lake Lamoille premium actually work?

If your property touches Lake Lamoille, the reservoir, or the Green River, stop comping against in-town sales. The premium is real — 30% to 50% above the median, sometimes more for direct waterfront with usable dock frontage.

The mistake buyers and sellers make most often is using a Morrisville cape sale as a comp for a lake house, or a lake house sale as a comp for a cape. They are not the same asset. They are not the same buyer pool. They do not behave the same in a slow year.

Should I bother with a valuation or just check Zillow?

If you are a buyer eyeballing a property, the Zillow index is a starting point. If you are a seller preparing to list, or a buyer preparing to write an offer, the Morristown valuation tool is the second step.

The third step — the one that costs nothing and matters most — is talking through the comps the AVM cannot see: the kitchen that was gutted last spring, the septic that needs replacement, the road that was re-paved since the last sale.

Zillow does not know about any of that. The MLS comps we pull every week do. The buyer who shows up to an offer with our valuation in hand and the seller's actual condition notes in mind is the buyer who wins the negotiation without paying the over-asking premium that ended 2024's deals.

Questions buyers and sellers ask us about Morristown

Will Vermont home prices drop in 2026?

National forecasts for 2026 put price growth at three to four percent. Vermont's Lamoille County has held a narrower range. We expect Morrisville to finish 2026 somewhere between flat and up two percent — gains driven by the low end of inventory tightening, not by the high end appreciating further.

Is Morristown still affordable for first-time buyers?

At a $371K median and 5.9% to 6.2% mortgage rates, the monthly cost is real but the structure works. Lamoille County first-time buyer programs, USDA rural development loans, and Vermont state housing finance programs all stack on top of the median. Talk to a local lender before you self-select out.

How is Morristown different from Hyde Park or Johnson?

Morrisville carries the village density — Copley, restaurants, the Route 100 commercial corridor. Hyde Park is more residential and more spread out. Johnson carries Northern Vermont University housing demand and a smaller core. Pricing reflects the difference; the three towns trade at different price points within a few miles of each other.

Should I sell now or wait until spring?

Inventory is rising but the ski-season rental window is open. We time listings to buyer intent: a ski-country property lists late summer; a primary residence lists early spring; a lake house lists when the docks are visible. There is no universal answer — talk through your specific property and we will tell you when.

Do you have clients who overpaid in 2022?

Yes. Several of them are refinancing now. If you are in that group, the conversation we are having is not whether to sell. It is how to position the asset through the next three years until the market recovers the comparables. We do this every week.

Where to Go Next

New England Landmark Realty · 26 N Main Street Suite 2, Waterbury, VT 05676 · Office (802) 253-4711 · Toll-Free (866) 324-2427 · Tony's cell (802) 233-4107 · www.nelandmark.com

.